


Capital One 360 Performance Savings™
Bankrate score: 4.5 out of 5Member FDIC
- APY as of 9/29/2026
- 3.10%
- Minimum balance for APY
- $0
- Estimated earnings
- $1,550
- Bankrate score
- Bankrate score: 4.5 out of 5
A high-yield savings account can be a safe place to earn interest on your money while keeping it easily accessible for emergencies and planning for economic downturns. Today's top savings rate is 4.20% APY offered by Happen Bank, which is around six times the current national average of 0.65% APY.
In addition to a high APY, the best high-yield savings accounts don’t charge fees and have low minimum deposit requirements. The accounts on this list are Bankrate’s highest-rated savings accounts from FDIC banks or NCUA credit unions.
These are sponsored offers rated highly by us for competitive rates, fees, and minimums. .
Showing 5 of 5
No amount yet in total interest earned
Our expert’s curated selection of competitive savings account offers. Bankrate's editorial team selects these offers based on competitive rates, minimal fees, and overall value to consumers. Our experts regularly review and update these picks to ensure they represent the best options available. How we choose our picks
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | CIT Bank APY | National average APY |
|---|---|---|
| 09/22/2026 | 3.75% | 0.63% |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Western State APY | National average APY |
|---|---|---|
| 09/22/2026 | 4.00% | 0.63% |
| 09/15/2026 | 4.00% | 0.63% |
| 09/08/2026 | 4.00% | 0.63% |
| 09/01/2026 | 4.00% | 0.63% |
| 08/25/2026 | 4.00% | 0.62% |
| 08/18/2026 | 4.00% | 0.62% |
| 08/11/2026 | 4.00% | 0.62% |
| 08/04/2026 | 4.00% | 0.62% |
| 07/28/2026 | 0.15% | 0.61% |
| 07/21/2026 | 0.15% | 0.61% |
| 07/14/2026 | 0.15% | 0.61% |
| 07/07/2026 | 0.15% | 0.61% |
| 06/30/2026 | 0.15% | 0.61% |
| 06/23/2026 | 0.15% | 0.61% |
| 06/16/2026 | 0.15% | 0.61% |
| 06/09/2026 | 0.15% | 0.61% |
| 06/02/2026 | 0.15% | 0.61% |
| 05/26/2026 | 0.15% | 0.61% |
| 05/19/2026 | 0.15% | 0.61% |
| 05/12/2026 | 0.15% | 0.61% |
| 05/05/2026 | 0.15% | 0.61% |
| 04/28/2026 | 0.15% | 0.59% |
| 04/21/2026 | 0.15% | 0.59% |
| 04/14/2026 | 0.15% | 0.59% |
| 04/07/2026 | 0.15% | 0.59% |
| 03/31/2026 | 0.15% | 0.60% |
| 03/24/2026 | 0.15% | 0.60% |
| 03/17/2026 | 0.15% | 0.60% |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | LendingClub APY | National average APY |
|---|---|---|
| 09/22/2026 | 4.00% | 0.63% |
| 09/16/2026 | 4.00% | 0.63% |
| 09/09/2026 | 4.00% | 0.63% |
| 09/01/2026 | 4.00% | 0.63% |
| 08/26/2026 | 4.00% | 0.62% |
| 08/19/2026 | 4.00% | 0.62% |
| 08/12/2026 | 4.00% | 0.62% |
| 08/05/2026 | 4.00% | 0.62% |
| 07/29/2026 | 4.00% | 0.61% |
| 07/22/2026 | 4.00% | 0.61% |
| 07/15/2026 | 4.00% | 0.61% |
| 07/08/2026 | 4.00% | 0.61% |
| 06/30/2026 | 4.00% | 0.61% |
| 06/24/2026 | 4.00% | 0.61% |
| 06/17/2026 | 4.00% | 0.61% |
| 06/09/2026 | 4.00% | 0.61% |
| 06/03/2026 | 4.00% | 0.61% |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Accordia APY | National average APY |
|---|---|---|
| 09/22/2026 | 4.00% | 0.63% |
| 09/15/2026 | 4.00% | 0.63% |
| 09/08/2026 | 4.00% | 0.63% |
| 09/01/2026 | 4.00% | 0.63% |
| 08/25/2026 | 4.00% | 0.62% |
| 08/18/2026 | 5.00% | 0.62% |
| 08/11/2026 | 4.00% | 0.62% |
| 08/04/2026 | 4.00% | 0.62% |
| 07/28/2026 | 4.00% | 0.61% |
| 07/21/2026 | 3.90% | 0.61% |
| 07/14/2026 | 3.90% | 0.61% |
| 07/07/2026 | 3.90% | 0.61% |
| 06/30/2026 | 3.90% | 0.61% |
| 06/23/2026 | 3.90% | 0.61% |
| 06/16/2026 | 3.90% | 0.61% |
| 06/09/2026 | 3.90% | 0.61% |
| 06/02/2026 | 3.90% | 0.61% |
| 05/26/2026 | 3.90% | 0.61% |
| 05/19/2026 | 3.90% | 0.61% |
| 05/12/2026 | 3.90% | 0.61% |
| 05/05/2026 | 3.90% | 0.61% |
| 04/28/2026 | 3.90% | 0.59% |
| 04/21/2026 | 3.90% | 0.59% |
| 04/14/2026 | 3.90% | 0.59% |
| 04/07/2026 | 3.90% | 0.59% |
| 03/31/2026 | 3.90% | 0.60% |
| 03/24/2026 | 3.90% | 0.60% |
| 03/17/2026 | 3.90% | 0.60% |
| 03/10/2026 | 3.90% | 0.60% |
| 03/03/2026 | 3.90% | 0.60% |
| 02/24/2026 | 3.90% | 0.60% |
| 02/17/2026 | 3.90% | 0.60% |
| 02/10/2026 | 3.90% | 0.60% |
| 02/03/2026 | 3.90% | 0.60% |
| 01/27/2026 | 3.90% | 0.62% |
| 01/20/2026 | 3.90% | 0.62% |
| 01/13/2026 | 3.90% | 0.62% |
| 01/06/2026 | 4.00% | 0.62% |
| 12/30/2025 | 4.00% | 0.61% |
| 12/23/2025 | 4.00% | 0.61% |
| 12/16/2025 | 4.00% | 0.61% |
| 12/09/2025 | 4.00% | 0.61% |
| 12/02/2025 | 4.00% | 0.61% |
| 11/25/2025 | 4.00% | 0.62% |
| 11/18/2025 | 4.00% | 0.62% |
| 11/11/2025 | 4.00% | 0.62% |
| 11/04/2025 | 4.00% | 0.62% |
| 10/28/2025 | 4.00% | 0.62% |
| 10/21/2025 | 4.00% | 0.62% |
| 10/14/2025 | 4.00% | 0.62% |
| 10/07/2025 | 4.00% | 0.62% |
| 09/30/2025 | 4.00% | N/A |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Vio Bank APY | National average APY |
|---|---|---|
| 09/22/2026 | 4.01% | 0.63% |
| 09/15/2026 | 3.95% | 0.63% |
| 09/08/2026 | 3.99% | 0.63% |
| 09/01/2026 | 3.99% | 0.63% |
| 08/25/2026 | 3.99% | 0.62% |
| 08/18/2026 | 3.99% | 0.62% |
| 08/11/2026 | 3.99% | 0.62% |
| 08/04/2026 | 4.00% | 0.62% |
| 07/28/2026 | 4.00% | 0.61% |
| 07/21/2026 | 4.00% | 0.61% |
| 07/14/2026 | 4.00% | 0.61% |
| 07/07/2026 | 4.01% | 0.61% |
| 06/30/2026 | 4.01% | 0.61% |
| 06/23/2026 | 4.01% | 0.61% |
| 06/16/2026 | 4.01% | 0.61% |
| 06/09/2026 | 4.01% | 0.61% |
| 06/02/2026 | 4.03% | 0.61% |
| 05/26/2026 | 4.03% | 0.61% |
| 05/19/2026 | 4.03% | 0.61% |
| 05/12/2026 | 4.03% | 0.61% |
| 05/05/2026 | 4.03% | 0.61% |
| 04/28/2026 | 4.03% | 0.59% |
| 04/21/2026 | 4.03% | 0.59% |
| 04/14/2026 | 4.03% | 0.59% |
| 04/07/2026 | 4.03% | 0.59% |
| 03/31/2026 | 4.03% | 0.60% |
| 03/24/2026 | 4.03% | 0.60% |
| 03/17/2026 | 4.03% | 0.60% |
| 03/10/2026 | 4.03% | 0.60% |
| 03/03/2026 | 4.03% | 0.60% |
| 02/24/2026 | 4.03% | 0.60% |
| 02/17/2026 | 4.03% | 0.60% |
| 02/10/2026 | 4.02% | 0.60% |
| 02/03/2026 | 4.02% | 0.60% |
| 01/27/2026 | 4.02% | 0.62% |
| 01/20/2026 | 4.09% | 0.62% |
| 01/13/2026 | 4.09% | 0.62% |
| 01/06/2026 | 4.09% | 0.62% |
| 12/30/2025 | 4.16% | 0.61% |
| 12/23/2025 | 4.16% | 0.61% |
| 12/16/2025 | 4.16% | 0.61% |
| 12/09/2025 | 4.16% | 0.61% |
| 12/02/2025 | 4.16% | 0.61% |
| 11/25/2025 | 4.16% | 0.62% |
| 11/18/2025 | 4.21% | 0.62% |
| 11/11/2025 | 4.21% | 0.62% |
| 11/04/2025 | 4.21% | 0.62% |
| 10/28/2025 | 4.26% | 0.62% |
| 10/21/2025 | 4.26% | 0.62% |
| 10/14/2025 | 4.31% | 0.62% |
| 10/07/2025 | 4.31% | 0.62% |
| 09/30/2025 | 4.31% | N/A |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Bread Savings APY | National average APY |
|---|---|---|
| 09/22/2026 | 3.95% | 0.63% |
| 09/15/2026 | 3.95% | 0.63% |
| 09/08/2026 | 3.95% | 0.63% |
| 09/01/2026 | 3.95% | 0.63% |
| 08/25/2026 | 3.95% | 0.62% |
| 08/18/2026 | 3.95% | 0.62% |
| 08/11/2026 | 3.95% | 0.62% |
| 08/04/2026 | 3.95% | 0.62% |
| 07/21/2026 | 3.95% | 0.61% |
| 07/14/2026 | 3.95% | 0.61% |
| 07/07/2026 | 3.95% | 0.61% |
| 06/30/2026 | 3.95% | 0.61% |
| 06/23/2026 | 3.95% | 0.61% |
| 06/16/2026 | 4.00% | 0.61% |
| 06/09/2026 | 4.00% | 0.61% |
| 06/02/2026 | 4.00% | 0.61% |
| 05/26/2026 | 4.00% | 0.61% |
| 05/19/2026 | 4.00% | 0.61% |
| 05/12/2026 | 4.00% | 0.61% |
| 05/05/2026 | 4.00% | 0.61% |
| 04/28/2026 | 4.00% | 0.59% |
| 04/21/2026 | 4.00% | 0.59% |
| 04/14/2026 | 4.00% | 0.59% |
| 04/07/2026 | 4.00% | 0.59% |
| 03/31/2026 | 4.00% | 0.60% |
| 03/24/2026 | 4.00% | 0.60% |
| 03/17/2026 | 4.00% | 0.60% |
| 03/10/2026 | 4.00% | 0.60% |
| 03/03/2026 | 4.00% | 0.60% |
| 02/24/2026 | 4.00% | 0.60% |
| 02/17/2026 | 4.00% | 0.60% |
| 02/10/2026 | 4.00% | 0.60% |
| 02/03/2026 | 4.00% | 0.60% |
| 01/27/2026 | 4.00% | 0.62% |
| 01/20/2026 | 4.00% | 0.62% |
| 01/13/2026 | 4.05% | 0.62% |
| 01/06/2026 | 4.05% | 0.62% |
| 12/29/2025 | 4.05% | 0.61% |
| 11/25/2025 | 4.15% | 0.62% |
| 11/11/2025 | 4.20% | 0.62% |
| 11/03/2025 | 4.20% | 0.62% |
| 10/28/2025 | 4.20% | 0.62% |
| 10/21/2025 | 4.20% | 0.62% |
| 10/07/2025 | 4.25% | 0.62% |
| 09/30/2025 | 4.25% | N/A |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | EverBank APY | National average APY |
|---|---|---|
| 09/18/2026 | 3.90% | 0.63% |
| 09/11/2026 | 3.90% | 0.63% |
| 09/04/2026 | 3.90% | 0.63% |
| 08/28/2026 | 3.90% | 0.62% |
| 08/21/2026 | 3.90% | 0.62% |
| 08/17/2026 | 3.90% | 0.62% |
| 08/07/2026 | 3.90% | 0.62% |
| 07/31/2026 | 3.90% | 0.61% |
| 07/24/2026 | 3.90% | 0.61% |
| 07/17/2026 | 3.90% | 0.61% |
| 07/10/2026 | 3.90% | 0.61% |
| 07/02/2026 | 3.90% | 0.61% |
| 06/26/2026 | 3.90% | 0.61% |
| 06/18/2026 | 3.90% | 0.61% |
| 06/12/2026 | 3.90% | 0.61% |
| 06/05/2026 | 3.90% | 0.61% |
| 05/29/2026 | 3.90% | 0.61% |
| 05/22/2026 | 3.90% | 0.61% |
| 05/15/2026 | 3.90% | 0.61% |
| 05/08/2026 | 3.90% | 0.61% |
| 05/01/2026 | 3.90% | 0.61% |
| 04/24/2026 | 3.90% | 0.59% |
| 04/17/2026 | 3.90% | 0.59% |
| 04/10/2026 | 3.90% | 0.59% |
| 04/03/2026 | 3.90% | 0.59% |
| 03/27/2026 | 3.90% | 0.60% |
| 03/20/2026 | 3.90% | 0.60% |
| 03/13/2026 | 3.90% | 0.60% |
| 03/06/2026 | 3.90% | 0.60% |
| 02/27/2026 | 3.90% | 0.60% |
| 02/20/2026 | 3.90% | 0.60% |
| 02/13/2026 | 3.90% | 0.60% |
| 02/06/2026 | 3.90% | 0.60% |
| 01/30/2026 | 3.90% | 0.62% |
| 01/23/2026 | 3.90% | 0.62% |
| 01/16/2026 | 3.90% | 0.62% |
| 01/09/2026 | 3.90% | 0.62% |
| 01/05/2026 | 3.90% | 0.62% |
| 12/26/2025 | 3.90% | 0.61% |
| 12/19/2025 | 3.90% | 0.61% |
| 12/16/2025 | 4.05% | 0.61% |
| 12/05/2025 | 4.05% | 0.61% |
| 12/01/2025 | 4.05% | 0.61% |
| 11/21/2025 | 4.05% | 0.62% |
| 11/14/2025 | 4.05% | 0.62% |
| 11/11/2025 | 4.05% | 0.62% |
| 10/31/2025 | 4.05% | 0.62% |
| 10/24/2025 | 4.05% | 0.62% |
| 10/17/2025 | 4.05% | 0.62% |
| 10/10/2025 | 4.05% | 0.62% |
| 10/03/2025 | 4.05% | 0.62% |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Popular Direct APY | National average APY |
|---|---|---|
| 09/22/2026 | 3.90% | 0.63% |
| 09/15/2026 | 3.90% | 0.63% |
| 09/08/2026 | 3.90% | 0.63% |
| 09/01/2026 | 3.90% | 0.63% |
| 08/26/2026 | 3.90% | 0.62% |
| 08/19/2026 | 3.90% | 0.62% |
| 08/11/2026 | 3.90% | 0.62% |
| 08/05/2026 | 3.90% | 0.62% |
| 07/28/2026 | 3.90% | 0.61% |
| 07/22/2026 | 3.90% | 0.61% |
| 07/14/2026 | 3.90% | 0.61% |
| 07/08/2026 | 3.90% | 0.61% |
| 06/30/2026 | 3.90% | 0.61% |
| 06/24/2026 | 3.90% | 0.61% |
| 06/17/2026 | 3.90% | 0.61% |
| 06/09/2026 | 3.90% | 0.61% |
| 06/02/2026 | 3.90% | 0.61% |
| 05/26/2026 | 3.90% | 0.61% |
| 05/20/2026 | 3.90% | 0.61% |
| 05/12/2026 | 3.90% | 0.61% |
| 05/05/2026 | 3.90% | 0.61% |
| 04/29/2026 | 3.90% | 0.59% |
| 04/21/2026 | 3.90% | 0.59% |
| 04/14/2026 | 3.90% | 0.59% |
| 04/07/2026 | 3.90% | 0.59% |
| 03/31/2026 | 3.90% | 0.60% |
| 03/24/2026 | 3.90% | 0.60% |
| 03/17/2026 | 3.90% | 0.60% |
| 03/11/2026 | 3.90% | 0.60% |
| 03/03/2026 | 3.90% | 0.60% |
| 02/24/2026 | 3.90% | 0.60% |
| 02/18/2026 | 3.90% | 0.60% |
| 02/11/2026 | 3.90% | 0.60% |
| 02/03/2026 | 3.90% | 0.60% |
| 01/28/2026 | 3.90% | 0.62% |
| 01/20/2026 | 3.90% | 0.62% |
| 01/12/2026 | 3.90% | 0.62% |
| 01/07/2026 | 3.90% | 0.62% |
| 12/31/2025 | 3.90% | 0.61% |
| 12/24/2025 | 3.90% | 0.61% |
| 12/15/2025 | 3.90% | 0.61% |
| 12/10/2025 | 4.00% | 0.61% |
| 12/02/2025 | 4.00% | 0.61% |
| 11/26/2025 | 4.00% | 0.62% |
| 11/19/2025 | 4.00% | 0.62% |
| 11/11/2025 | 4.00% | 0.62% |
| 11/05/2025 | 4.00% | 0.62% |
| 10/29/2025 | 4.05% | 0.62% |
| 10/22/2025 | 4.05% | 0.62% |
| 10/14/2025 | 4.05% | 0.62% |
| 10/07/2025 | 4.05% | 0.62% |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Live Oak APY | National average APY |
|---|---|---|
| 09/22/2026 | 4.00% | 0.63% |
| 09/15/2026 | 4.00% | 0.63% |
| 09/08/2026 | 4.00% | 0.63% |
| 09/01/2026 | 3.90% | 0.63% |
| 08/25/2026 | 3.90% | 0.62% |
| 08/18/2026 | 3.80% | 0.62% |
| 08/11/2026 | 3.80% | 0.62% |
| 08/04/2026 | 3.80% | 0.62% |
| 07/28/2026 | 3.80% | 0.61% |
| 07/21/2026 | 3.80% | 0.61% |
| 07/14/2026 | 3.80% | 0.61% |
| 07/07/2026 | 3.80% | 0.61% |
| 06/30/2026 | 3.80% | 0.61% |
| 06/23/2026 | 3.80% | 0.61% |
| 06/16/2026 | 3.80% | 0.61% |
| 06/09/2026 | 3.80% | 0.61% |
| 06/02/2026 | 3.80% | 0.61% |
| 05/26/2026 | 3.80% | 0.61% |
| 05/19/2026 | 3.80% | 0.61% |
| 05/12/2026 | 3.80% | 0.61% |
| 05/05/2026 | 3.80% | 0.61% |
| 04/28/2026 | 3.80% | 0.59% |
| 04/21/2026 | 3.80% | 0.59% |
| 04/14/2026 | 3.80% | 0.59% |
| 04/07/2026 | 3.80% | 0.59% |
| 03/31/2026 | 3.80% | 0.60% |
| 03/24/2026 | 3.80% | 0.60% |
| 03/17/2026 | 3.80% | 0.60% |
| 03/10/2026 | 3.80% | 0.60% |
| 03/03/2026 | 3.80% | 0.60% |
| 02/24/2026 | 3.80% | 0.60% |
| 02/17/2026 | 3.80% | 0.60% |
| 02/10/2026 | 3.80% | 0.60% |
| 02/03/2026 | 3.80% | 0.60% |
| 01/27/2026 | 3.80% | 0.62% |
| 01/20/2026 | 3.80% | 0.62% |
| 01/13/2026 | 3.80% | 0.62% |
| 01/06/2026 | 3.80% | 0.62% |
| 12/30/2025 | 3.90% | 0.61% |
| 12/23/2025 | 3.90% | 0.61% |
| 12/16/2025 | 3.90% | 0.61% |
| 12/09/2025 | 3.90% | 0.61% |
| 12/02/2025 | 3.90% | 0.61% |
| 11/25/2025 | 3.90% | 0.62% |
| 11/18/2025 | 3.90% | 0.62% |
| 11/11/2025 | 3.90% | 0.62% |
| 11/04/2025 | 3.90% | 0.62% |
| 10/28/2025 | 4.00% | 0.62% |
| 10/21/2025 | 4.00% | 0.62% |
| 10/14/2025 | 4.00% | 0.62% |
| 10/07/2025 | 4.00% | 0.62% |
| 09/30/2025 | 4.00% | N/A |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Zynlo Bank APY | National average APY |
|---|---|---|
| 09/22/2026 | 3.85% | 0.63% |
| 09/16/2026 | 3.85% | 0.63% |
| 09/09/2026 | 3.85% | 0.63% |
| 09/01/2026 | 3.85% | 0.63% |
| 08/26/2026 | 3.85% | 0.62% |
| 08/18/2026 | 3.85% | 0.62% |
| 08/11/2026 | 3.85% | 0.62% |
| 07/28/2026 | 3.85% | 0.61% |
| 07/14/2026 | 3.85% | 0.61% |
| 07/08/2026 | 3.85% | 0.61% |
| 06/30/2026 | 3.85% | 0.61% |
| 06/24/2026 | 3.85% | 0.61% |
| 06/17/2026 | 3.85% | 0.61% |
| 06/09/2026 | 3.85% | 0.61% |
| 06/02/2026 | 3.85% | 0.61% |
| 05/26/2026 | 3.85% | 0.61% |
| 05/19/2026 | 3.85% | 0.61% |
| 05/13/2026 | 3.85% | 0.61% |
| 05/05/2026 | 3.85% | 0.61% |
| 04/29/2026 | 3.85% | 0.59% |
| 04/21/2026 | 3.85% | 0.59% |
| 04/14/2026 | 3.85% | 0.59% |
| 03/31/2026 | 3.85% | 0.60% |
| 03/24/2026 | 3.85% | 0.60% |
| 03/18/2026 | 3.85% | 0.60% |
| 03/11/2026 | 3.85% | 0.60% |
| 03/04/2026 | 3.85% | 0.60% |
| 02/25/2026 | 3.85% | 0.60% |
| 02/10/2026 | 3.85% | 0.60% |
| 02/04/2026 | 3.85% | 0.60% |
| 01/28/2026 | 3.85% | 0.62% |
| 01/20/2026 | 3.85% | 0.62% |
| 01/14/2026 | 3.85% | 0.62% |
| 01/07/2026 | 3.85% | 0.62% |
| 12/31/2025 | 3.85% | 0.61% |
| 12/15/2025 | 4.05% | 0.61% |
| 12/09/2025 | 4.05% | 0.61% |
| 11/25/2025 | 4.05% | 0.62% |
| 11/18/2025 | 4.20% | 0.62% |
| 11/12/2025 | 4.20% | 0.62% |
| 11/05/2025 | 4.20% | 0.62% |
| 10/28/2025 | 4.20% | 0.62% |
| 10/21/2025 | 4.20% | 0.62% |
| 10/14/2025 | 4.20% | 0.62% |
| 09/30/2025 | 4.35% | N/A |

See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Colorado Federal Savings Bank APY | National average APY |
|---|---|---|
| 09/22/2026 | 3.85% | 0.63% |
| 09/15/2026 | 3.85% | 0.63% |
| 09/08/2026 | 3.85% | 0.63% |
| 09/01/2026 | 3.85% | 0.63% |
| 08/25/2026 | 3.85% | 0.62% |
| 08/18/2026 | 3.85% | 0.62% |
| 08/11/2026 | 3.85% | 0.62% |
| 08/04/2026 | 3.85% | 0.62% |
| 07/28/2026 | 3.85% | 0.61% |
| 07/21/2026 | 3.85% | 0.61% |
| 07/14/2026 | 3.80% | 0.61% |
| 07/07/2026 | 3.80% | 0.61% |
| 06/30/2026 | 3.80% | 0.61% |
| 06/23/2026 | 3.80% | 0.61% |
| 06/16/2026 | 3.80% | 0.61% |
| 06/09/2026 | 3.80% | 0.61% |
| 06/02/2026 | 3.80% | 0.61% |
| 05/26/2026 | 3.80% | 0.61% |
| 05/19/2026 | 3.80% | 0.61% |
| 05/12/2026 | 3.80% | 0.61% |
| 05/05/2026 | 3.80% | 0.61% |
| 04/28/2026 | 3.80% | 0.59% |
| 04/21/2026 | 3.80% | 0.59% |
| 04/14/2026 | 3.80% | 0.59% |
| 04/07/2026 | 3.80% | 0.59% |
| 03/31/2026 | 3.80% | 0.60% |
| 03/24/2026 | 3.80% | 0.60% |
| 03/17/2026 | 3.80% | 0.60% |
| 03/10/2026 | 3.80% | 0.60% |
| 03/03/2026 | 4.00% | 0.60% |
| 02/24/2026 | 4.00% | 0.60% |
| 02/17/2026 | 4.00% | 0.60% |
| 02/10/2026 | 4.00% | 0.60% |
| 02/03/2026 | 4.00% | 0.60% |
| 01/27/2026 | 4.00% | 0.62% |
| 01/20/2026 | 4.00% | 0.62% |
| 01/13/2026 | 4.00% | 0.62% |
| 01/06/2026 | 4.00% | 0.62% |
| 12/30/2025 | 4.00% | 0.61% |
| 12/23/2025 | 4.00% | 0.61% |
| 12/16/2025 | 4.00% | 0.61% |
| 12/09/2025 | 4.00% | 0.61% |
| 12/02/2025 | 4.00% | 0.61% |
| 11/25/2025 | 4.00% | 0.62% |
| 11/18/2025 | 4.00% | 0.62% |
| 11/11/2025 | 4.00% | 0.62% |
| 11/04/2025 | 4.00% | 0.62% |
| 10/28/2025 | 4.00% | 0.62% |
| 10/21/2025 | 4.00% | 0.62% |
| 10/14/2025 | 4.00% | 0.62% |
| 10/07/2025 | 4.10% | 0.62% |
| 09/30/2025 | 4.10% | N/A |
See how rates for this account have changed over time. Interact with the trend lines to view APY by date.
| Date | Forbright Bank APY | National average APY |
|---|---|---|
| 09/22/2026 | 3.85% | 0.63% |
| 09/15/2026 | 3.85% | 0.63% |
| 09/08/2026 | 3.85% | 0.63% |
| 09/01/2026 | 3.85% | 0.63% |
| 08/25/2026 | 3.85% | 0.62% |
| 08/18/2026 | 3.85% | 0.62% |
| 08/11/2026 | 3.85% | 0.62% |
| 08/04/2026 | 3.85% | 0.62% |
| 07/28/2026 | 3.85% | 0.61% |
| 07/21/2026 | 3.85% | 0.61% |
| 07/14/2026 | 3.85% | 0.61% |
| 07/07/2026 | 3.85% | 0.61% |
| 06/30/2026 | 3.85% | 0.61% |
| 06/23/2026 | 3.85% | 0.61% |
| 06/16/2026 | 3.85% | 0.61% |
| 06/09/2026 | 3.85% | 0.61% |
| 06/02/2026 | 3.85% | 0.61% |
| 05/26/2026 | 3.85% | 0.61% |
| 05/19/2026 | 3.85% | 0.61% |
| 05/12/2026 | 3.85% | 0.61% |
| 05/05/2026 | 3.85% | 0.61% |
| 04/28/2026 | 3.85% | 0.59% |
| 04/21/2026 | 3.85% | 0.59% |
| 04/14/2026 | 3.85% | 0.59% |
| 04/07/2026 | 3.85% | 0.59% |
| 03/31/2026 | 3.85% | 0.60% |
| 03/24/2026 | 3.85% | 0.60% |
| 03/17/2026 | 3.85% | 0.60% |
| 03/10/2026 | 3.85% | 0.60% |
| 03/03/2026 | 3.85% | 0.60% |
| 02/24/2026 | 3.85% | 0.60% |
| 02/17/2026 | 3.85% | 0.60% |
| 02/10/2026 | 3.85% | 0.60% |
| 02/03/2026 | 3.85% | 0.60% |
| 01/27/2026 | 3.85% | 0.62% |
| 01/20/2026 | 3.85% | 0.62% |
| 01/13/2026 | 3.85% | 0.62% |
| 01/06/2026 | 4.00% | 0.62% |
| 12/30/2025 | 4.00% | 0.61% |
| 12/23/2025 | 4.00% | 0.61% |
| 12/16/2025 | 4.00% | 0.61% |
| 12/09/2025 | 4.00% | 0.61% |
| 12/02/2025 | 4.00% | 0.61% |
| 11/25/2025 | 4.00% | 0.62% |
| 11/18/2025 | 4.00% | 0.62% |
| 11/11/2025 | 4.00% | 0.62% |
| 11/04/2025 | 4.00% | 0.62% |
| 10/28/2025 | 4.00% | 0.62% |
| 10/21/2025 | 4.00% | 0.62% |
| 10/14/2025 | 4.00% | 0.62% |
| 10/07/2025 | 4.25% | 0.62% |
| 09/30/2025 | 4.25% | N/A |
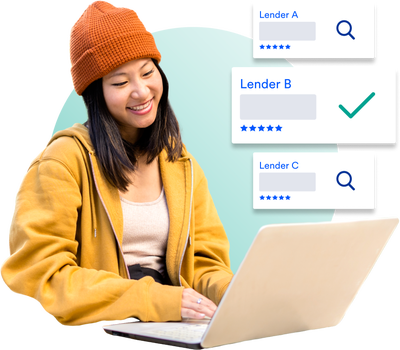
See savings and CD rates from different banks and credit unions in one place, so you can quickly compare your options.
Check the rate, terms and requirements, then pick the account that helps your savings grow faster.
Click through to the bank or credit union to open your account and start earning interest.
Savings account rates have been declining in recent years — in response to six Federal Reserve rate cuts in 2024 and 2025. The Fed has kept rates steady so far in 2026 and competitive savings rates have also continued to stay about the same.
But even some competitive rates may not be beating inflation anymore. The Consumer Price Index (CPI; a common and closely followed gauge of inflation) was reported as 3.4% on an annual basis for July — up significantly from 2.4% for February. That means if your savings APY is earning less than that, you are technically losing some purchasing power.
It's not just inflation working against savers — it's where they keep their money. Many of the nation's largest brick-and-mortar banks pay just 0.01% APY on their standard savings accounts. That translates to only $1 in interest per year on a $10,000 balance. Meanwhile, online-only banks — with far lower overhead than big banks with branches — sometimes offer APYs up to 400 times greater.
Whether or not your APY is outpacing inflation, keeping your money in a bank that’s paying a competitive rate helps you grow your savings more quickly.
It's especially a good time to open a high-yield savings account if:
It’s worth noting that typically, the country’s largest brick-and-mortar banks don’t make Bankrate’s top list — their savings account APYs sit at 0.01%, which is a fraction of what’s available elsewhere. That said, various high-earning accounts didn’t land on our list, yet they might work for you. Here are some strong options to consider:
| Axos Bank |
Axos Bank offers 4.21% APY for its ONE Savings account with no initial deposit minimums, fees or balance requirements. It’s not on our list because you have to bundle this account with Axos’ checking account. Axos also has an account that pays 3.75% with no bundling requirement. |
| Credit One Bank |
Credit One Bank's Jumbo High Yield Savings Account earns 4.00% APY — but you'll have to deposit a whopping $100,000 to open the account and earn that APY. |
| SoFi Bank |
By meeting some requirements, you can earn a 3.10% APY here — or up to 3.80% if you earn the bonus boost. Plus, you’ll automatically get a connected checking account that also earns interest, and you can organize your savings into “vaults.” |
| Varo Bank |
You can earn 3.75% APY on up to $5,000 in your Varo savings account (but you have to meet requirements to get that rate). |
When shopping around for the right account, take a look at Bankrate’s expert reviews of popular banks, many of which offer competitive rates. Also consider these important features when choosing the best high-yield savings account:
Your savings will grow more quickly when you're earning higher interest. It's easy to assume your money is earning something reasonable if it's parked at a big, familiar bank — but these often pay just 0.01% APY on standard savings, well below the national average of 0.65%. Meanwhile, competitive accounts are earning up to around 400 times what the biggest banks pay. The difference between a high APY and a near-zero one could add up to hundreds, if not thousands, in interest over time.
Rather than letting a monthly service fee eat into your savings, find an account that won’t charge this pesky fee. The options on Bankrate’s list typically don’t charge such a fee.
Being able to withdraw your money easily is important, especially in an emergency. You may be able to take money out of your savings account at an ATM, using a peer-to-peer money transfer app or through an ACH transfer. You may also want to seek banks that allow unlimited withdrawals each month, rather than restricting you to six.
A high-yield savings account provides easy access to your cash, making it a good place to earn some interest while you build up an emergency fund or save for goals such as a wedding or down payment on a house. While you’re adding to your savings, consider using the interest you earn to pay for discretionary expenses such as a streaming service or a gym membership.
If you’re saving for multiple goals in a single account, it can pay to choose an account that allows you to separate the funds into categories. This way, it’s easy to track how much you have saved for each goal. For instance, Ally Bank lets you create up to 30 savings "buckets."
One way to grow your nest egg is by setting up recurring automatic transfers. Moving a set amount from your checking to your savings every payday helps ensure you’ll save consistently and reach your goals.
Calculate your savings
Estimate how much your money could grow with a high-yield savings account.
Plan for emergencies
Read about the best places to keep your emergency fund.
Create a savings strategy
Determine the best amount to save every month.
Average savings account rates
Stay up to date on how your savings yield compares to the national average.


Bankrate researches over 100 banks and credit unions, including some of the largest financial institutions, online-only banks, regional banks and credit unions with both open and restrictive membership policies.
To find the best high-yield savings accounts, we rated these institutions on their savings account’s APYs, monthly fees, minimum deposit requirements, access to funds and more. Banks and credit unions receive penalties against their overall scores for each consent decree, penalty in a case brought by a federal regulator or in a certified, federal class-action lawsuit, or adverse federal judgment for harming deposits customers.
The highest-rated savings accounts from broadly-available banks and credit unions, that also had the highest APYs, made our list. Learn more about how we choose the best banking products and our methodology for reviewing banks.
We appreciate your feedback
Thank you for taking the time to share your experience.


